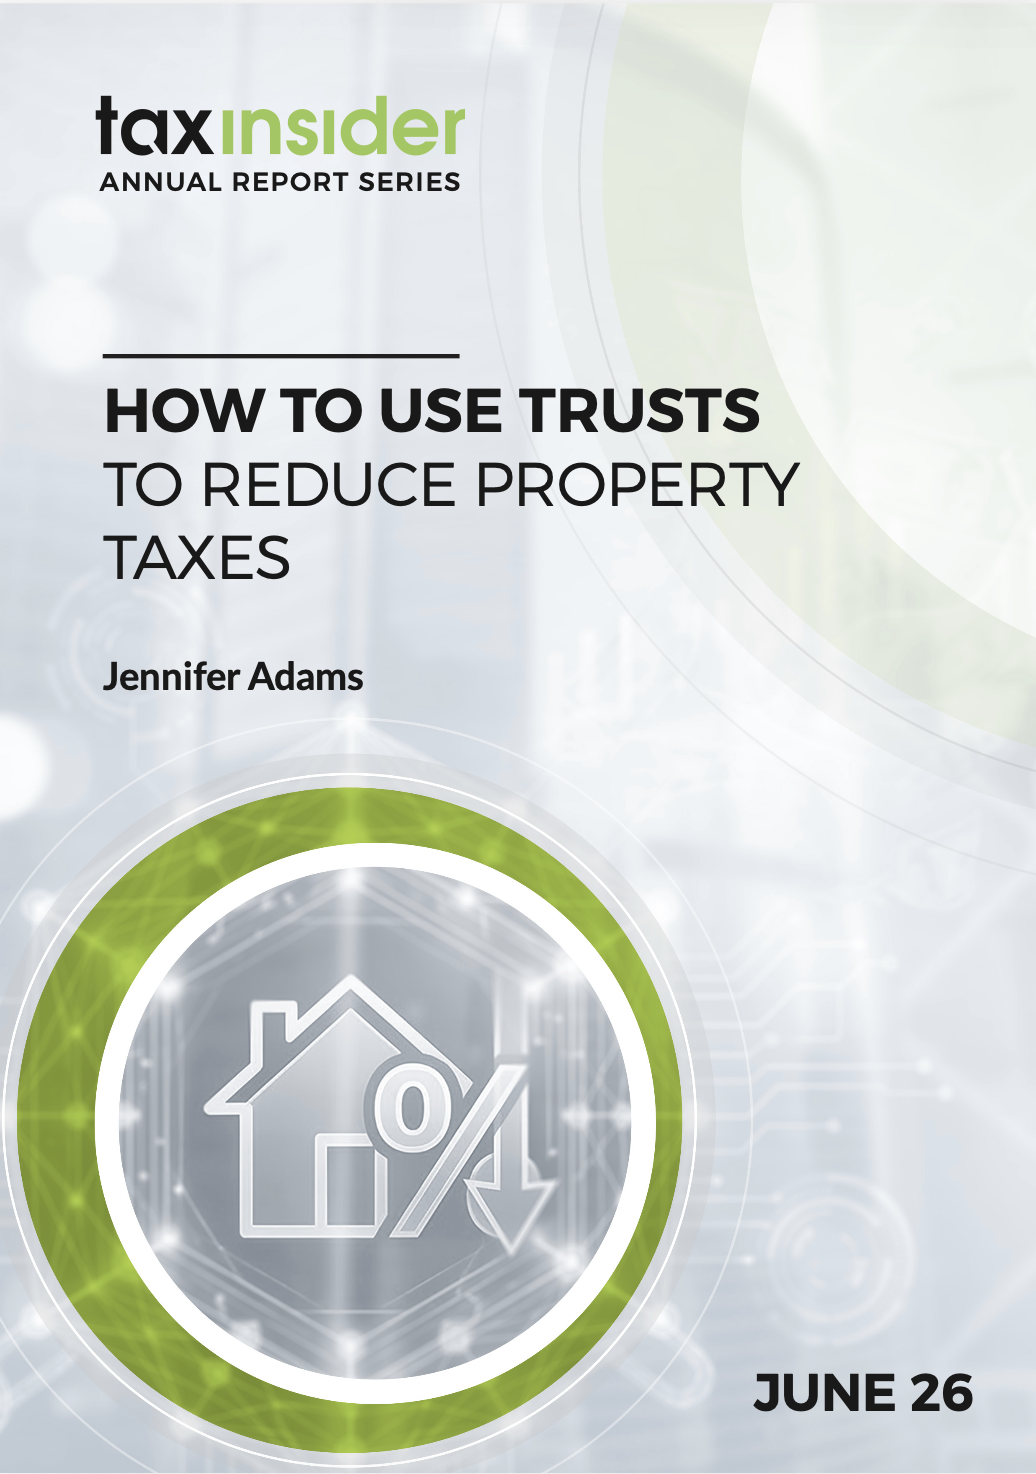
How to Use Trusts to Reduce Property Taxes
How to choose, set up and manage trusts for rental property and the family home, including income tax, capital gains tax, inheritance tax and trust compliance.

** New 2026-27 Edition Now Available - 40% End of Month Discount **
Property Trust Tax Planning for Landlords and Property Owners
By Jennifer Adams, TEP
Trusts can protect property for the next generation and, when structured correctly, reduce income tax, capital gains tax and inheritance tax on rental property and the family home. But each type of trust is taxed differently, and the wrong choice, or the right trust set up the wrong way, can create tax charges the owner never expected.
Written by Jennifer Adams, a qualified member of the Society of Trust and Estate Practitioners (STEP), this practical guide explains how property owners and their advisers can choose the right type of trust, set it up and run it correctly, and use it to plan around income tax, capital gains tax, inheritance tax and stamp duty land tax.
What Is a Property Trust?
A trust is a private legal arrangement under which the settlor transfers assets to trustees, who hold them for the benefit of the beneficiaries. The trustees become the legal owners but cannot use the assets as their own. A property trust is simply a trust whose assets include property, such as a buy-to-let, a main residence or farmland, and any trust that holds land must be evidenced in writing.
The main types are qualifying interest in possession (QIIP) trusts, where a beneficiary, usually a "life tenant", is entitled to the income as it arises; discretionary trusts, where the trustees decide who receives income and capital; and bare trusts, where the beneficiary is absolutely entitled to both. Each type is taxed differently.
Trusts, Property Taxes and the Traps to Avoid
Property trusts are one of the most underused tools in personal tax planning and one of the most misunderstood. The assumption that they are complicated, expensive and best left to the very wealthy has kept many property owners from planning that can deliver substantial savings. Yet with the nil-rate band frozen at £325,000 until 5 April 2031, rising property values mean more estates are crossing the inheritance tax threshold, and individual landlords receive only basic rate relief on residential mortgage interest.
The traps are real. A settlor who puts their home into a trust but carries on living there is caught by the gift with reservation of benefit rules, so the property stays in their estate. A discretionary trust of the family home can lose the £175,000 residence nil-rate band, and a trust holding nothing but a property may have no cash to pay for insurance and repairs.
Get it right, and a property trust can protect assets, reduce tax across multiple heads, and provide a structured mechanism for passing wealth to the next generation. Get it wrong, and the consequences range from unexpected HMRC challenges to failed gifts, clawback exposure and unintended inheritance tax liabilities.
What This Report Covers
In seven chapters and 13 worked examples, this 24,000+ word guide to the 2026/27 rules will show you how to:
- Understand what a trust is and how property trusts are legally constituted
- Identify when setting up a trust is the right planning choice and when it is not
- Avoid the critical trap that affects single property trusts and can undermine an entire structure
- Minimise income tax on rental and investment property income using trusts
- Minimise capital gains tax on property disposals through careful trust planning
- Minimise inheritance tax exposure using trusts, including the use of nil rate band planning
- Choose between different trust types — discretionary, life interest, bare and others — and understand which suits each situation
- Plan effectively for minors, including the use of 18-25 trusts
- Gift property to children or other family members in a tax-efficient and legally robust way
- Transfer property to a spouse using a trust structure without triggering unintended tax charges
- Understand what a deed of trust is and how it operates in practice
- Identify and manage clawback risk in property trust arrangements
- Plus much more…
Trust types, trust deeds and compliance
Why set up a trust and where its protection against bankruptcy, divorce and post-death claims can fail, the three certainties needed to create one, and what the trust deed and letter of wishes should cover. It also covers the roles of settlor, trustee and beneficiary, registration with HMRC's Trust Registration Service and the SA900 trust tax return.
Income tax on rental income held in trust
How QIIP and discretionary trusts are taxed on rental income, why trusts get no personal or property allowance, and how mandating income to a life tenant works. It covers the 45% trust rate for discretionary trusts, the tax pool, and how relief for mortgage interest works in each type of trust.
Capital gains tax, holdover relief and SDLT
When CGT arises on putting property into a trust, selling it, transferring it out or ending the trust, and when holdover relief can defer the gain (most buy-to-let properties do not qualify as business assets). It also explains why holdover relief cannot be combined with principal private residence relief, how a mortgage can make a gift into trust liable to SDLT, and the 5% supplement that applies automatically when discretionary trustees buy residential property.
Inheritance tax charges on relevant property trusts
How the relevant property regime applies to most lifetime trusts created since 22 March 2006: the lifetime charge on transfers above the £325,000 nil-rate band, the ten-year periodic charge of up to 6% and exit charges when property leaves the trust. It also covers excluded property trusts under the long-term UK residence test, accumulated income and pilot trusts.
Inheritance tax planning: NRB trusts, the RNRB, APR and BPR
Nil-rate band discretionary trusts, loan trusts, discounted gift trusts and nil-rate band will trusts over a share of the family home, and why the settlor cannot keep living in a home they have given away. The guide shows how a deed of variation can save the residence nil-rate band that a discretionary will trust would lose, and explains APR and BPR in trusts, including clawback and the £2.5m cap on 100% relief from 6 April 2026.
Trusts for minors and grandchildren
How the settlement rules affect gifts to children, including why income over £100 a year from money a parent gives their child through a bare trust is taxed on the parent. It also explains trusts for bereaved minors and age 18 to 25 trusts, which only parents can create, and why a grandparent's trust "to such of my grandchildren as reach 21" loses the residence nil-rate band.
Who Will Benefit From This Report?
This guide is essential reading for any property owner, whether residential landlord, buy-to-let investor or owner of a family property portfolio, who wants to reduce their exposure to income tax, capital gains tax and inheritance tax through trust planning. It is also relevant to parents and grandparents planning to pass property on to the next generation.
It is equally valuable for accountants, tax advisers and solicitors advising clients with property held personally, jointly or within family structures, and for in-house finance professionals dealing with property-owning entities.
If you own property, advise clients who do, or need a reliable reference for trust-based property planning, this guide belongs on your shelf.
About Jennifer Adams TEP
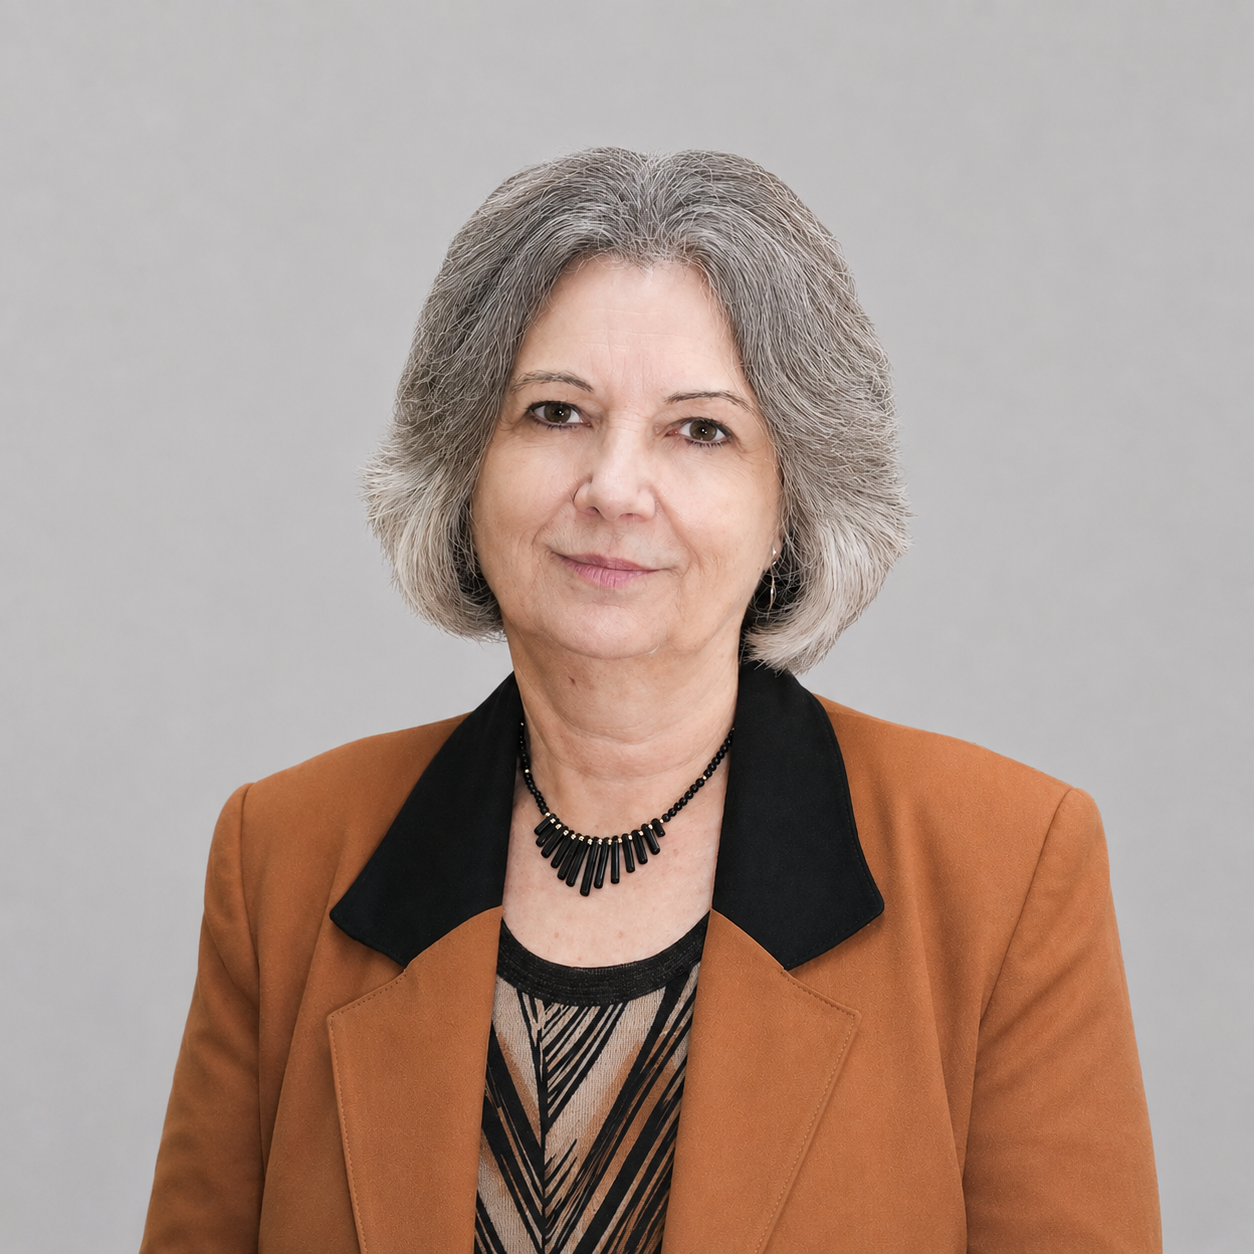 Jennifer Adams TEP, FATT, FCG is an accountant and has been a professional business author for over 25 years, specialising in property tax and corporate governance. She is Consulting Editor of AccountingWEB and the proprietor of Naldrett Accountants, a two-office practice based in Surrey and Dorset. She also owns a portfolio of properties, so she is well placed to advise on the tax problems landlords may face.
Jennifer has written for many of the leading specialist providers of legal, tax and regulatory publications, including Butterworths, Tolleys, LexisNexis, BDO, Sage, the Chartered Governance Institute and the Chartered Insurance Institute. She is a Fellow of the Association of Taxation Technicians and a qualified member of the Society of Trust and Estate Practitioners (STEP).
She is a regular contributor to Tax Insider and Property Tax Insider, and the author of the Tax Insider book 101 Property Tax Tips.
Read an excerpt from this report: Using Trusts: The types of Trusts.



