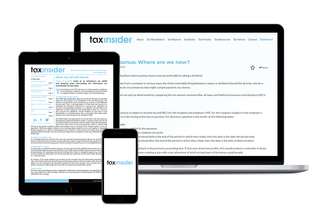
 DIGITAL
- Instant access to 1439 digital articles
- Downloadable PDFs
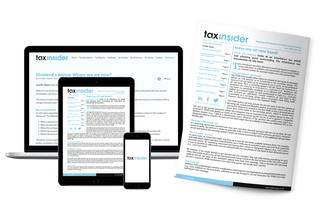 DIGITAL + PRINT
- Instant access to 1439 digital articles
- Downloadable PDFs
- Print copy delivered monthly
-
Suitable for all business typesLtd companies, sole traders & partnerships
-
Digital format (or add print too)Whatever your preference, you've got it
-
Published every monthSo you're always kept up to date
-
90-day money back guarantee100% of your money back, no quibble
-
Instant back catalogue accessOver 1439 articles to help you save tax
-
No commitmentNo minimum tie-ins, cancel anytime
Written by leading UK tax professionals
Every article, tip and strategy in Tax Insider is written and reviewed by practising accountants, Chartered Tax Advisers and specialist tax consultants, including contributors such as Mark McLaughlin, Peter Rayney and Malcolm Finney. You're getting advice from people who advise real clients on real tax problems, not generic guidance.
New articles published
in November 2026
-
£1m IHT Free: The Routes Most People Overlook
Lottery winnings of £1m are not exempt from inheritance tax (IHT) once they become part of a person's estate. Winnings paid out to members of any formal National Lottery or syndicate are exempt from IHT provided a written agreement was drawn up before the win; this ensures each person receives what legally belongs to them within the agreement rather than a taxable ‘gift’ from the first named lottery participant.
Jon Golding looks at ways of securing a £1m IHT-free exemption for gifts and legacies.
 Joint Accounts and IHT: The 50:50 Assumption That Can Cost You
When it comes to working out the potential inheritance tax (IHT) liability on an individual's estate, it might be assumed that funds in a joint account belong equally to the joint account holders (e.g., mother and adult son).
This might actually be the case – but not automatically so. As with many other questions in tax, the answer is: it depends.
This article considers the IHT treatment of joint accounts in England, Wales and Northern Ireland. In Scotland, the position may differ (see the HM Revenue and Customs (HMRC) Inheritance Tax Manual at IHTM15051 and IHTM15054).
Mark McLaughlin warns that it is not necessarily straightforward to ascertain how much money in a joint account belongs to each account holder for inheritance tax purposes.
 No Will, No Say: What Intestacy Really Costs
When the actor and comedian Rik Mayall died in June 2014, many were astonished to learn that he did so intestate (i.e., he had no will outlining what was to happen to his estate); there was clearly no tax planning either, resulting in a £60,000 inheritance tax bill.
Whilst this was a fairly high-profile intestacy case, over 51,000 letters of administration were issued in the UK in 2024 (i.e. where estates were intestate), so Rik Mayall was not the only one.
Chris Thorpe looks at what happens to an individual’s estate on death if there is no valid will.
 Reclaiming VAT: Do You Have More Than Just an Invoice?
Businesses have to overcome a number of hurdles to claim back input tax, so it is not just as simple as having a purchase invoice.
Any input tax claimed by a business must relate to a supply that has actually taken place. For example, where a payment has been made and an invoice received but the goods or services were never physically supplied, input tax should not be claimed as no supply has actually taken place.Andrew Needham looks at recovering input tax and warns that a business may need more evidence than the purchase invoice.
-
Hit Your Pension Allowance? Could You Pay Into Someone Else’s?
Putting money away for retirement is generally sensible, and pensions are highly tax-efficient ways of saving for the future.
However, those with income between £260,000 and £360,000 have a tapered annual allowance (possibly as low as £10,000); high pension contributors may hit their annual allowance maximum (£60,000) and those who have already started accessing their pension have a separate limit (i.e., £10,000 with no carry forward).
What if someone wants to pay more into pensions, or to help out others with their retirement savings?Tristan Noyes looks at the implications and opportunities of funding other people’s pensions.
 Rent a Room Relief: Easy on Income Tax, Tricky on CGT
Most property owners who let out a room will be aware of rent-a-room relief, the income tax exemption for up to £7,500 a year of gross receipts (£3,750 if income is shared with another) from furnished accommodation in their only or main property. They will also expect any gain on disposal to be covered by capital gains tax (CGT) principal private residence (PPR) relief.
Jennifer Adams considers the capital gains tax position when someone takes one or more lodgers into their home.
 Capital Allowances: Are You Using the Right One for Each Asset?
Companies cannot deduct capital expenditure when calculating their taxable profits; relief is instead given through the capital allowances system.
There are a number of allowances available for expenditure on plant and machinery, and these should be used wisely to maximise relief.
Sarah Bradford explores the capital allowance claims available to companies, and how best to use them.
-
Q&As with Arthur Weller
Some of our most popular articles
-
Tax implications of awarding shares to family members
The employment-related securities legislation deals with arrangements involving shares and securities provided by reason of employment where the full value of the employment reward provided to the employee is not included in the salary package and is charged to tax.
Jennifer Adams considers the tax implications of shares in a family company being awarded or gifted to family members of employees.
- Decisions, decisions! Partnership or limited company?
A sole trader looking to expand their business might be weighing up the ‘pros’ and ‘cons’ of a partnership or a limited company. They are very different, with not only very different tax consequences, but functions as well.
Chris Thorpe looks at partnerships and companies and considers which business model might be best.
 Don’t write off your chances of tax relief!
Under the loan relationships rules for companies, debits on loan arrangements are not deductible for corporation tax purposes in some circumstances.
Kevin Read highlights a recent case concerning the loan relationship rules for companies.
-
Who has tipped HMRC off?
When HM Revenue and Customs (HMRC) opens a tax return enquiry, the natural reaction of most taxpayers is to speculate about the reason why their tax return has been selected. In fact, HMRC does not need an excuse to open a tax return enquiry; a small proportion of tax returns are simply selected at random. .
Mark McLaughlin looks at whether a taxpayer can find out if an HMRC enquiry has been opened as the result of an accusation made by a third party.
-
Remuneration in 2024/25 - Important Considerations
When considering the tricky matter of remuneration planning, there are two things to consider; the amount of remuneration, and what form it takes.
Chris Thorpe looks at what to watch out for with regard to paying employees and directors.
- Alternative ways of paying staff tax-efficiently
Despite the reduction in National Insurance contributions (NICs) in Spring Budget 2024, more employees are paying tax at higher rates on their earnings due to the freezing of tax thresholds. Some may find that any pay rise or bonus attracts additional tax and NICs such that the net pay increase is minimal.
Jennifer Adams looks at some alternatives to rewarding an employee with a pay rise or a bonus.
-
A popular ‘exit’ strategy when a shareholder is retiring
Mark McLaughlin looks at company purchases of own shares and warns not to become too focused on the more difficult rules for capital treatment.
A company purchase of its own shares from a shareholder is a popular ‘exit’ strategy when an individual shareholder is retiring, or a dissenting shareholder is departing.
-
Q&As with Arthur Weller
Subscription Benefits
We asked our subscribers what they love about Tax Insider.
These are the top 7 reasons that they gave us:
Monthly Newsletter
DIGITAL
- Instant access to 1439 digital articles
- Downloadable PDFs
DIGITAL + PRINT
- Instant access to 1439 digital articles
- Downloadable PDFs
- Print copy delivered monthly
-
Suitable for all business typesLtd companies, sole traders & partnerships
-
Digital format (or add print too)Whatever your preference, you've got it
-
Published every monthSo you're always kept up to date
-
90-day money back guarantee100% of your money back, no quibble
-
Instant back catalogue accessOver 1439 articles to help you save tax
-
No commitmentNo minimum tie-ins, cancel anytime
Tax Insider…